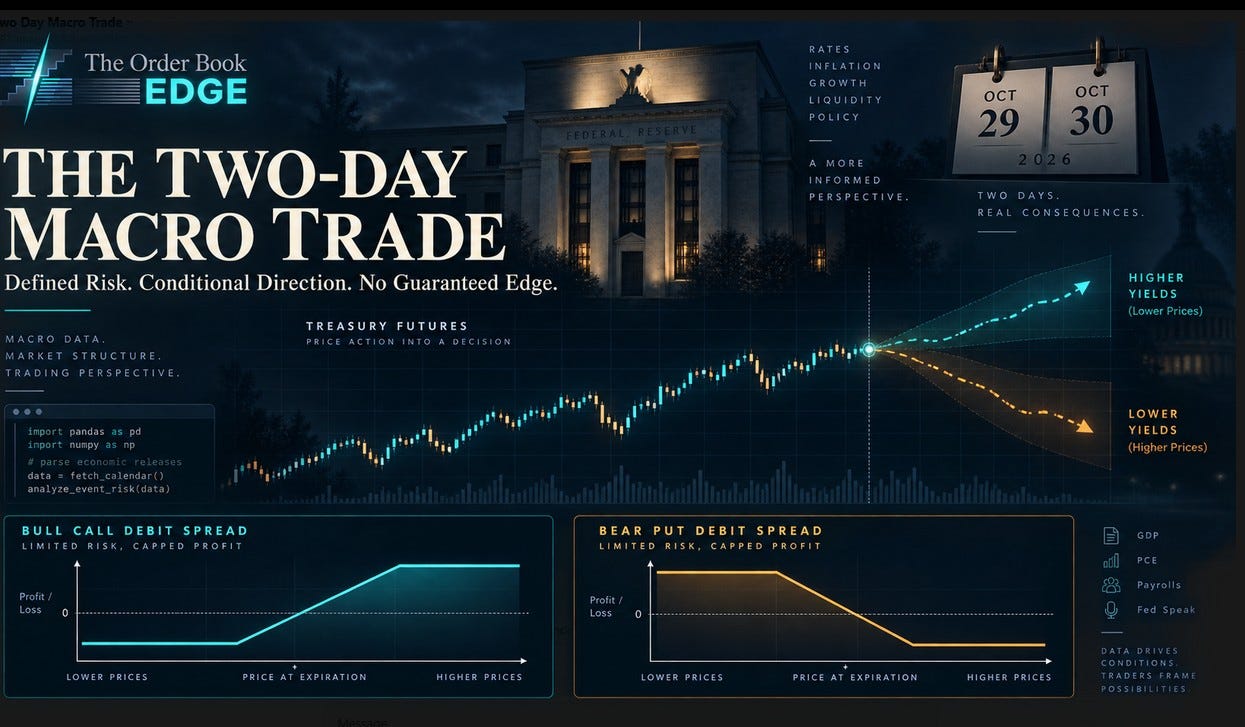

Research date: October 28, 2026
Trading window: Thursday, October 29, through Friday, October 30, 2026
The conclusion upfront: The supplied report does not establish which trade will be most profitable. It contains material contract errors, inconsistent prices, and unsupported claims about institutional positioning. My preferred strategy to evaluate, rather than execute blindly, is a short-dated, defined-risk directional spread on 10-year Treasury futures, entered only after Thursday’s economic releases and market confirmation.
A bearish Treasury reaction would favor a put debit spread; a bullish reaction would favor a call debit spread. If neither direction nor pricing is attractive, the strategy is no trade.
Disclosure: This is educational research, not personalized investment advice. Futures and options can produce substantial losses. All trade prices, premiums, scenario probabilities, and performance examples below are explicitly hypothetical unless identified as verified facts. I have not obtained a synchronized, executable options chain or run a backtest of the proposed entry rules.