
Research date: October 27, 2026. Based on the supplied “trading_report.pdf,” with essential calendar and contract details checked against official sources.
The short answer: The PDF does not contain sufficiently reliable evidence to identify the most profitable trade for the next two trading days. My preferred structure to evaluate is a short-dated Nasdaq-100 options debit spread, entered only after the Federal Reserve announcement establishes a tradable direction: a put spread for a confirmed downside move, or a call spread for a confirmed upside move.
That is a conditional strategy preference—not a verified trading edge, a live trade recommendation, or a promise of maximum profit.
For this article, “the next two trading days” means Wednesday, October 28, and Thursday, October 29, 2026. The Federal Reserve meeting is October 27–28, not October 28–29 as parts of the PDF suggest. The decision and press conference fall on Wednesday; important economic releases follow Thursday morning. (federalreserve.gov)
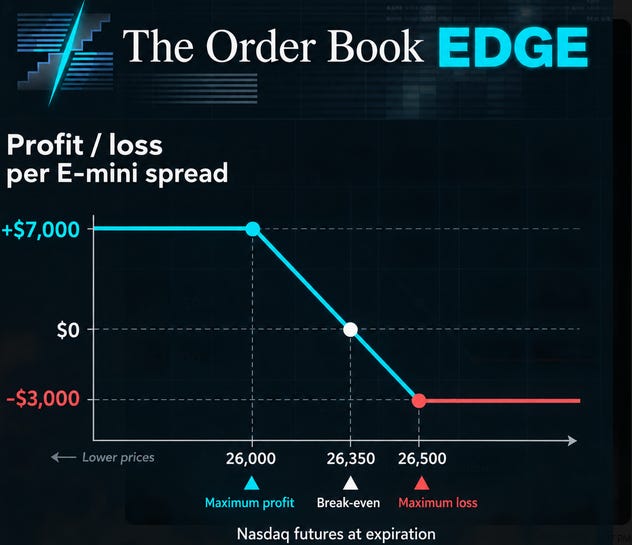
Important: I have not verified executable, real-time futures-option quotations. Every strike, premium, profit figure, and trade-management example below is hypothetical. The payoff diagrams show expiration economics before fees, not guaranteed liquidation values during the two-day holding period. Futures can produce losses exceeding the initial margin deposit; options can lose their entire premium. (cftc.gov)