
Executive Summary: The October 2026 Inflection Point
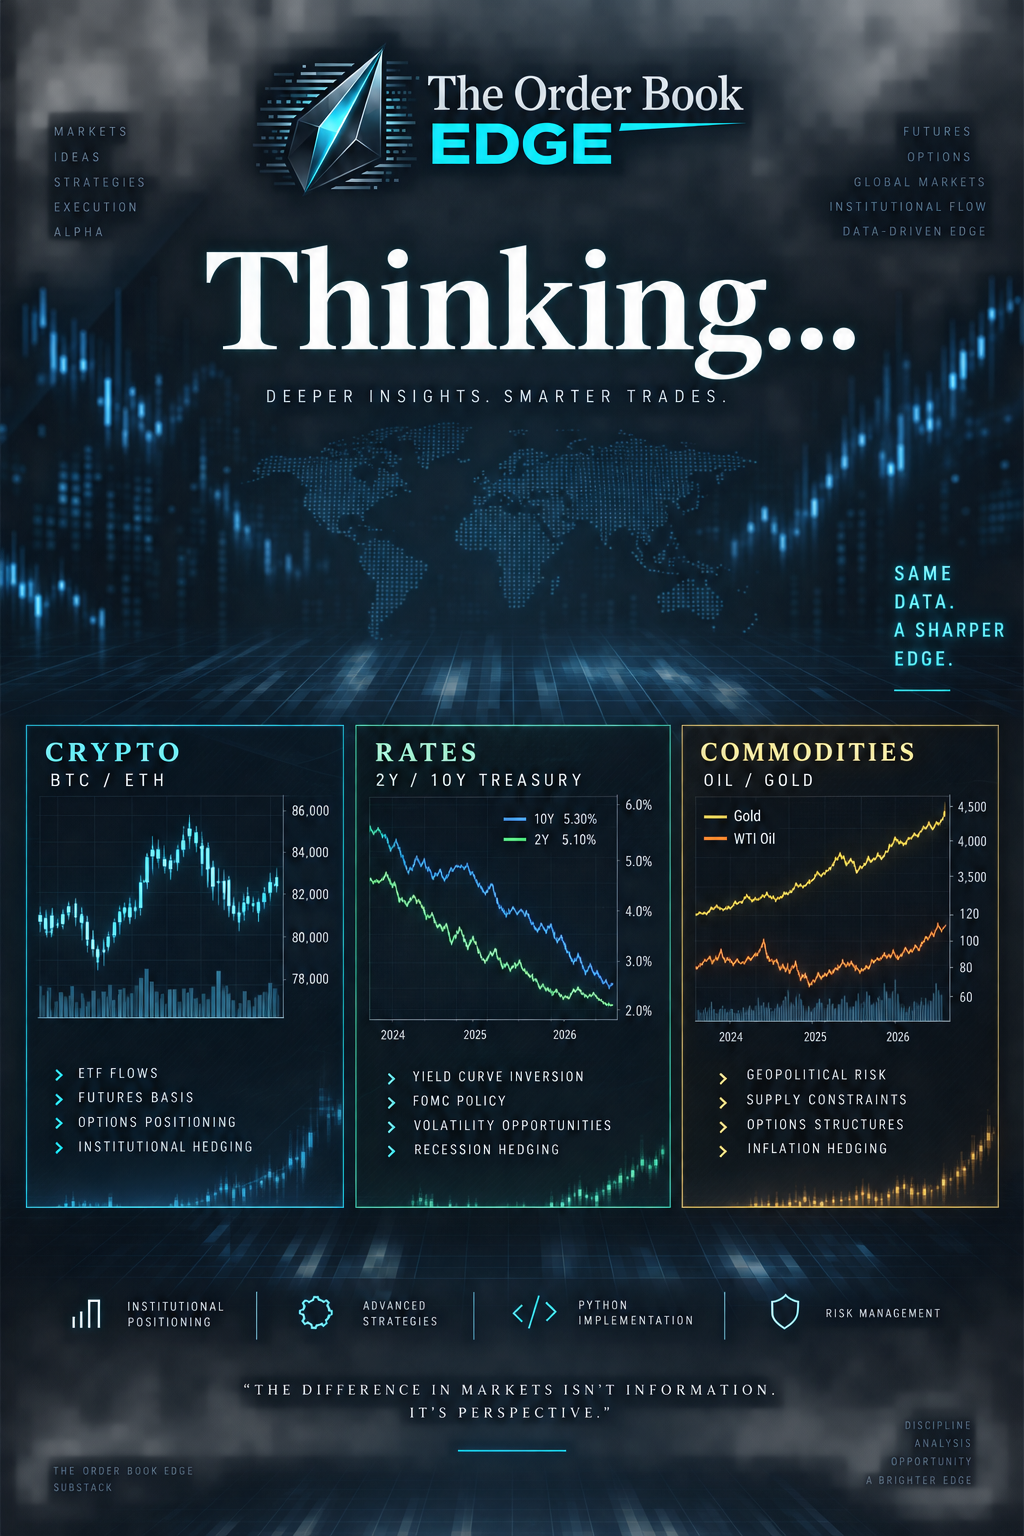
Markets are at a critical juncture. Bitcoin has just experienced its first significant ETF outflow in three weeks—$1.2 billion exiting spot products—while CME futures maintain a stubborn $500–$800 premium to spot. Simultaneously, the 2s10s Treasury curve has inverted to -45 basis points (the deepest since 2000), signaling recession fears that contradict the 82% probability of a December Fed hike priced into Fed Funds futures. Crude oil is oscillating between $95 and $106 per barrel on Middle East supply fears, while gold has decoupled from the dollar, trading at $4,200 with a -0.65 correlation to DXY.
Institutional investors—pension funds, sovereign wealth funds, and commodity trading advisors (CTAs)—are not gambling on direction. They are executing three systematic, defined-risk strategies that dominate the Commitment of Traders (COT) reports and options flow data:
The Crypto Basis Harvest & Volatility Selling (Cash-and-carry arbitrage with short-dated straddle sales)
The Treasury Curve De-Inversion Play (2s10s steepener with convexity overlays)
The Geopolitical Commodity Call Spread Stack (Defined-risk bullish exposure in oil and gold)
This report dissects these strategies with institutional-grade granularity. We provide the exact contract specifications, the options Greeks driving the trades, and—crucially—Python code for every calculation, from basis annualization to portfolio Value-at-Risk (VaR). By the end, you will understand not just what the institutions are doing, but how to replicate it, and which specific variant offers the highest expected value for the trading week of October 12–19, 2026.