

Executive Summary: The Structural Collisions of the Overnight Session
Overnight order flow across CME, ICE, and Eurex signaled an acute structural shift across rates, commodities, and digital assets. While headline equity indices (E-mini S&P ESZ6 and Nasdaq-100 NQZ6) have hovered near all-time highs, underlying market architecture is cracking under the strain of hawkish interest rate repricing and geopolitical escalations in the Middle East.
The intelligence synthesized in our overnight telemetry illustrates three dominant systemic catalysts currently driving capital reallocations:
The “Bonds Bomb” and Front-End Repricing: An exceptional surge in the US Composite PMI to 58.4 (a multi-year peak), paired with resilient initial jobless claims and narrowing current account deficits, has pushed the market to aggressively re-evaluate the Federal Reserve’s trajectory. Short-term interest rate (STIR) markets are pricing in a 60–75% probability of an additional 25–50 bps rate hike by December 2026, forcing 10-Year yields up 8 bps to test 4.35% (with peak cash real yields touching 2.40%).
Energy Margin Blowouts & Geopolitical Premium: The conflict corridor involving Israel and Iran, coupled with flight cancellations across the UAE and contested signals surrounding the Strait of Hormuz, has driven Brent (
BRNZ6) into deep backwardation (Dec 26 / Jun 27 spread at −$3.50/bbl-\$3.50/\text{bbl}−$3.50/bbl). Distillate crack spreads (HOZ6-CLZ6) reached historic levels of $108/bbl\$108/\text{bbl}$108/bbl, while RBOB crack spreads (RBZ6-CLZ6) widened to $62/bbl\$62/\text{bbl}$62/bbl.Volatility Divergence & Systemic De-risking: The MOVE Index has spiked to 125 (up 25% week-over-week), even as the equity VIX sits between 18 and 22. Under systematic mandate Rule 4.6, an 18–25 VIX regime paired with an extreme cross-asset volatility skew requires an immediate 25% to 50% risk-budget drawdown.
Below is an institutional analysis of overnight order-book telemetry, its transmission into today’s news flow, and actionable positioning across asset classes.
1. Rates & Fixed Income: Term Premium Unwinds and Hawkish Repricing
      YIELD CURVE & VOLATILITY TRANSMISSION
  US PMI 58.4 ──► Fed Hike Bets ──► MOVE Index Spike (125)
                          │
       ┌──────────────────┴──────────────────┐
       ▼                                     ▼
Front-End (SR3Z6, ZTZ6)              Back-End (ZNZ6, TNZ6, UBZ6)
Heavy Put Buying (95.00/94.75)       NOB Spread Widens / Duration Dump
Overnight Flow & Microstructure Dynamics
The rates complex experienced substantial institutional selling overnight. The primary catalyst was the US Composite PMI printing at 58.4, invalidating any remaining market expectations for near-term Fed easing.
Short-Term Rates (SOFR & Eurodollar): CME Three-Month SOFR futures (
SR3Z6) recorded massive institutional block trades (~5,000 contracts) at 94.85, locking in an implied terminal rate of 5.15% to 5.35%. Institutions aggressively boughtSR3Z695.00/94.75 put spreads at 12–15 bps (up from 8 bps last week). Eurodollar Dec 26 / Mar 27 spreads (GEZ6-GEH7) widened, reinforcing a “higher-for-longer” or incremental-hike scenario through mid-2027.Treasury Futures & Convexity Drag: Benchmark 10-Year Treasury Note futures (
ZNZ6/TYZ6) faced relentless shorting. Open interest rotated out of front months into December contracts, with large block purchases targetingZNZ6110-00 and 108-00 puts. Convexity hedging drove the MOVE index to 125, prompting institutions to purchaseZNZ6108/112 straddles at $1,200\$1,200$1,200 (up 25% WoW).Curve Reshaping: The 2s10s yield curve spread (
ZTZ6vs.ZNZ6) shifted from −15 bps-15\text{ bps}−15 bps up toward −5 bps-5\text{ bps}−5 bps, threatening to completely emerge from inversion. Concurrently, intermediate-to-long term structures witnessed severe stress: the NOB spread (Ultra 10-YearTNZ6vs. Ultra BondUBZ6) widened sharply as institutional duration-hedging concentrated sales into the 30-year sector (UBZ6).
Impact on Today’s Market News & Catalysts
Headline Shift: Morning macro headlines are shifting from “Recession Watch” to “Inflationary Second-Wave and Term-Premium Rebound.”
Sovereign Contagion: German Bunds (
FGBLZ6) broke down toward 3.57% yields, while French OATs (FOATZ6) rose to 4.68% (levels not seen since 2011). European sovereign spreads over Bunds widened (Italian BTPsFBTPZ6blew out by 96 bps), indicating that US monetary tightening is exporting sovereign volatility across the Atlantic.
What to Trade Today
The 2s5s10s Butterfly: Buy 5Y wings (
FVZ6) against selling 2Y (TUZ6/ZTZ6) and 10Y (TNZ6/ZNZ6). Intermediate yields will benefit from short-end pricing stability while terminal rates remain bounded.Financed Long Volatility via Put Spreads: Sell
TNZ6Dec 118 puts to buyTNZ6Dec 115 puts. This finances bearish duration exposure while protecting against Fed-pivot short squeezes.Cross-Atlantic Sovereign Arb: Long German Bund (
FGBLZ6) / Short Italian BTP (FBTPZ6) spread to exploit European periphery divergence under high global real yields.
Institutional Macro & Derivatives Briefing: From Overnight Globex Telemetry to Today’s Trading Playbook
Document Reference: trading_report.pdf (Institutional Strategy Telemetry)
Date of Analysis: September 25, 2026
Session Context: Overnight Execution Post-Mortem & Transition into US Cash Session
Target Audience: Systematic Traders, Multi-Asset Desks, Macro Portfolio Managers
Executive Summary: The Structural Collisions of the Overnight Session
Overnight order flow across CME, ICE, and Eurex signaled an acute structural shift across rates, commodities, and digital assets. While headline equity indices (E-mini S&P ESZ6 and Nasdaq-100 NQZ6) have hovered near all-time highs, underlying market architecture is cracking under the strain of hawkish interest rate repricing and geopolitical escalations in the Middle East.
The intelligence synthesized in our overnight telemetry (trading_report.pdf) illustrates three dominant systemic catalysts currently driving capital reallocations:
The “Bonds Bomb” and Front-End Repricing: An exceptional surge in the US Composite PMI to 58.4 (a multi-year peak), paired with resilient initial jobless claims and narrowing current account deficits, has pushed the market to aggressively re-evaluate the Federal Reserve’s trajectory. Short-term interest rate (STIR) markets are pricing in a 60% to 75% probability of an additional 25 to 50 bps rate hike by December 2026, forcing 10-Year yields up 8 bps to test 4.35% (with peak cash real yields touching 2.40%).
Energy Margin Blowouts & Geopolitical Premium: The conflict corridor involving Israel and Iran, coupled with flight cancellations across the UAE and contested signals surrounding the Strait of Hormuz, has driven Brent (
BRNZ6) into deep backwardation (Dec 26 / Jun 27 spread trading at a 3.50 dollar per barrel discount for the deferred contract). Distillate crack spreads reached historic levels of 108 dollars per barrel, while RBOB crack spreads widened to 62 dollars per barrel.Volatility Divergence & Systemic De-risking: The MOVE Index has spiked to 125 (up 25% week-over-week), even as the equity VIX sits between 18 and 22. Under systematic mandate Rule 4.6, an 18 to 25 VIX regime paired with an extreme cross-asset volatility skew requires an immediate 25% to 50% risk-budget drawdown.
Below is the pseudo-code logic tracking how the system governs risk sizing during this transition:
// Systematic Risk-Budget Sizing Engine (Rule 4.6)
FUNCTION calculate_portfolio_risk_budget(vix_value, move_index):
    risk_budget = 1.00  // Default 100% full allocation

    IF vix_value >= 18 AND vix_value < 25:
        risk_budget = risk_budget * 0.75  // Trim risk by 25%
    ELSE IF vix_value >= 25 AND vix_value < 35:
        risk_budget = risk_budget * 0.50  // Trim risk by 50%
    ELSE IF vix_value >= 35:
        risk_budget = risk_budget * 0.25  // Emergency de-risk by 75%
    END IF

    // Bond Volatility Surcharge
    IF move_index > 120:
        risk_budget = risk_budget * 0.90  // Additional 10% haircut for convexity shock
    END IF

    RETURN risk_budget
END FUNCTION
1. Rates & Fixed Income: Term Premium Unwinds and Hawkish Repricing
      YIELD CURVE & VOLATILITY TRANSMISSION
  US PMI 58.4 ──► Fed Hike Bets ──► MOVE Index Spike (125)
                          │
       ┌──────────────────┴──────────────────┐
       ▼                                     ▼
Front-End (SR3Z6, ZTZ6)              Back-End (ZNZ6, TNZ6, UBZ6)
Heavy Put Buying (95.00/94.75)       NOB Spread Widens / Duration Dump
Overnight Flow & Microstructure Dynamics
The rates complex experienced substantial institutional selling overnight. The primary catalyst was the US Composite PMI printing at 58.4, invalidating any remaining market expectations for near-term Fed easing.
Short-Term Rates (SOFR & Eurodollar): CME Three-Month SOFR futures (
SR3Z6) recorded massive institutional block trades (around 5,000 contracts) at 94.85, locking in an implied terminal rate of 5.15% to 5.35%. Institutions aggressively boughtSR3Z695.00/94.75 put spreads at 12 to 15 bps (up from 8 bps last week). Eurodollar Dec 26 / Mar 27 spreads widened, reinforcing a “higher-for-longer” or incremental-hike scenario through mid-2027.Treasury Futures & Convexity Drag: Benchmark 10-Year Treasury Note futures (
ZNZ6/TYZ6) faced relentless shorting. Open interest rotated out of front months into December contracts, with large block purchases targetingZNZ6110-00 and 108-00 puts. Convexity hedging drove the MOVE index to 125, prompting institutions to purchaseZNZ6108/112 straddles at 1,200 dollars (up 25% WoW).Curve Reshaping: The 2s10s yield curve spread shifted from minus 15 bps up toward minus 5 bps, threatening to completely emerge from inversion. Concurrently, intermediate-to-long term structures witnessed severe stress: the NOB spread (Ultra 10-Year
TNZ6vs. Ultra BondUBZ6) widened sharply as institutional duration-hedging concentrated sales into the 30-year sector (UBZ6).
// Algorithm: Monitoring Yield Curve Inversion Exit
FUNCTION evaluate_curve_steepener(two_year_yield, ten_year_yield):
    curve_spread = ten_year_yield - two_year_yield

    IF curve_spread > -0.05 AND curve_spread < 0.00:
        SIGNAL = "ALERT: Curve Dis-inversion Imminent"
        ACTION = "Unwind 2s10s flatteners; initiate 10s30s steepeners"
    ELSE IF curve_spread >= 0.00:
        SIGNAL = "REGIME CHANGE: Yield Curve Normalized"
        ACTION = "Target long-end term premium unwinds"
    END IF

    RETURN ACTION
END FUNCTION
Impact on Today’s Market News & Catalysts
Headline Shift: Morning macro headlines are shifting from “Recession Watch” to “Inflationary Second-Wave and Term-Premium Rebound.”
Sovereign Contagion: German Bunds (
FGBLZ6) broke down toward 3.57% yields, while French OATs (FOATZ6) rose to 4.68% (levels not seen since 2011). European sovereign spreads over Bunds widened (Italian BTPsFBTPZ6blew out by 96 bps), indicating that US monetary tightening is exporting sovereign volatility across the Atlantic.
What to Trade Today
The 2s5s10s Butterfly: Buy 5Y wings (
FVZ6) against selling 2Y (TUZ6/ZTZ6) and 10Y (TNZ6/ZNZ6). Intermediate yields will benefit from short-end pricing stability while terminal rates remain bounded.Financed Long Volatility via Put Spreads: Sell
TNZ6Dec 118 puts to buyTNZ6Dec 115 puts. This finances bearish duration exposure while protecting against Fed-pivot short squeezes.Cross-Atlantic Sovereign Arb: Long German Bund (
FGBLZ6) / Short Italian BTP (FBTPZ6) spread to exploit European periphery divergence under high global real yields.
2. Energy Complex: War Premia, Severe Backwardation, and Refining Margins
                CRUDE SPREAD STRUCTURE
ICE Brent Dec 26 ($102.13) ──► Dec26/Jun27 Backwardation (-$3.50)
            ▲                                ▲
            │ Middle East Premium            │ Physical Shortage
NYMEX WTI Dec 26 ($95.00)  ──► Crack Spread HO-CL ($108/bbl ATH)
Overnight Flow & Microstructure Dynamics
Energy markets traded overnight with acute asymmetric right-tail skew. Geopolitical developments regarding Iranian diplomacy, contrasted against a surge in Saudi exports and threats to Gulf tanker transit, led to massive institutional positioning:
Crude Futures Dynamics: ICE Brent Dec 26 traded up to 102.13 dollars per barrel before settling near 100.00 dollars, while NYMEX WTI (
CLZ6) traded near 95.00 dollars per barrel. Net long positioning in ICE Brent reached 350,000 contracts (a 3-month high). Brent’s time-spread structure is backwardated: the Dec 26 vs. Jun 27 calendar spread widened to minus 3.50 dollars per barrel, pointing to an immediate physical deficit.Brent/WTI Differential: The spread widened between minus 3.50 and minus 4.00 dollars per barrel. The market is pricing a structural disruption premium into seaborne Brent that cannot be quickly bridged by domestic US shale, where production growth has moderated.
Historic Crack Spreads: In the refined products arena, the Heating Oil crack spread hit an all-time high of 108 dollars per barrel, while the Gasoline crack spread held at 62 dollars per barrel. Speculation over diesel availability, refinery runs, and global shipping disruptions pushed commercial refiners to buy
HOZ6futures outright while sellingCLZ6to lock in refining margins.Options Volatility Skew: Implied volatility on Brent jumped to 35% (calls commanding a 5 vol-point premium over puts), with heavy block trades in
BRNZ6110/120 call spreads.
// Algorithm: Refinery Crack Spread Arbitrage Logic
FUNCTION evaluate_distillate_refining_margin(heating_oil_price, crude_oil_price):
    // Standard barrel conversion for heating oil (cents per gallon to dollars per barrel)
    ho_barrel_price = heating_oil_price * 42
    crack_spread = ho_barrel_price - crude_oil_price

    IF crack_spread >= 100.00:
        POSITION = "Execute Long HO, Short CL (Lock Refining Margin)"
        RISK_MANAGEMENT = "Trail stop loss if spread drops below 95.00"
    ELSE:
        POSITION = "Hold / Monitor Crack Margins"
    END IF

    RETURN POSITION
END FUNCTION
Impact on Today’s Market News & Catalysts
Headline Shift: Mainstream financial wires will focus on headline consumer inflation numbers driven by the crude recovery (well above 90 to 100 dollars per barrel) and the historic spike in distillate fuel.
Supply Chain Transmission: Airlines and freight operators will face immediate earnings downgrades as crack spreads cascade through operating costs.
What to Trade Today
Long Brent / Short WTI Spread Trade: Enter long ICE Brent Dec 26 vs. short NYMEX WTI Dec 26 targeting a spread expansion beyond minus 5.00 dollars per barrel. Middle East risk premiums will disproportionately accrue to Brent.
Bull Call Spread in Brent: Buy
BRNZ6100 calls / sellBRNZ6110 calls. Implied vol skew allows for advantageous pricing along the upside corridor.Refining Margin Protection: Long the 3:2:1 crack spread (buying 3 barrels of crude, selling 2 barrels of gasoline and 1 barrel of heating oil, or using pure product vs crude equivalents) to monetize product scarcity over raw unrefined feedstock.
3. Currencies & FX: The “King Dollar” Liquidity Vacuum
                    DOLLAR INDEX SURGE
      DXY Dec 26 (106.50) ──► Overbought Daily RSI (70)
               │                        │
       ┌───────┴───────┐        ┌───────┴───────┐
       ▼               ▼        ▼               ▼
   EUR/USD (6EZ6)   USD/JPY  AUD/USD (6AZ6)  USD/INR (NDF)
   Breaks 1.05      Tests    Fails 0.67      Spikes to 84.00
                    152.00   (China Drag)    (EM Capital Flight)
Overnight Flow & Microstructure Dynamics
The US Dollar Index (DXZ6) advanced through 106.50 (with front-month tests at 101.11 to 106.50 depending on curve contract maturity), driving daily RSI metrics to 70. CFTC commitments show net long USD positioning at a 4-month peak of roughly 25 billion dollars.
EUR/USD (
6EZ6): Broke down to 1.0500. Institutional order flow was dominated by block buying of Dec 26 1.08 and 1.05 puts (around 5,000 contracts), reflecting divergence between a resilient Fed and an economically paralyzed, dovish European Central Bank.USD/JPY (
6JZ6): Traded past 152.00. While domestic Japanese intervention risks remain high, the correlation between USD/JPY and the US 10-Year yield (holding at positive 0.92) continues to overwhelm Bank of Japan jawboning. Traded options indicate institutions are buying 155.00 call spreads while hedging flash-crash intervention risk via deep out-of-the-money puts.Emerging Markets FX Stress (USD/INR): As reported in the telemetry, the Reserve Bank of India’s onshore/offshore gap widened. Non-Deliverable Forwards (NDFs) for USD/INR broke 84.00, while NSE 10Y Indian Government Bond futures suffered their worst decline in two months, demonstrating severe EM rate-hike contagion.
// Algorithm: Systematic Yield-FX Divergence Pairing
FUNCTION evaluate_fx_rate_divergence(us_yield_trend, ecb_posture, boj_action):
    IF us_yield_trend == "HAWKISH_EXPANSION" AND ecb_posture == "DOVISH":
        EXECUTE = "Open EUR/USD Bear Put Spread (1.05 / 1.02)"
    END IF

    IF us_yield_trend == "HAWKISH_EXPANSION" AND boj_action == "INACTIVE":
        EXECUTE = "Buy USD/JPY Calls with Out-Of-The-Money Protective Put"
    END IF

    RETURN EXECUTE
END FUNCTION
Impact on Today’s Market News & Catalysts
Headline Shift: Global trade terms are deteriorating under dollar dominance. Today’s news will focus on Asian and European central bank rhetoric attempting to defend currency pegs and curb imported inflation.
What to Trade Today
DXY Call Vertical: Buy
DXZ6105.00 / 107.00 call spreads. With US real yields rising, the path of least resistance remains higher.EUR/USD Downside Structuring: Execute Dec 26 1.05/1.02 put spreads. Financed by the low implied volatility of EUR options (10%), this position capitalizes on ECB policy divergence.
Fading Commodity Currencies: Short Australian Dollar futures (
6AZ6) against the USD, exploiting China’s slowing industrial demand (reflected in declining August steel output and falling Singapore iron ore futures,TIOZ6).
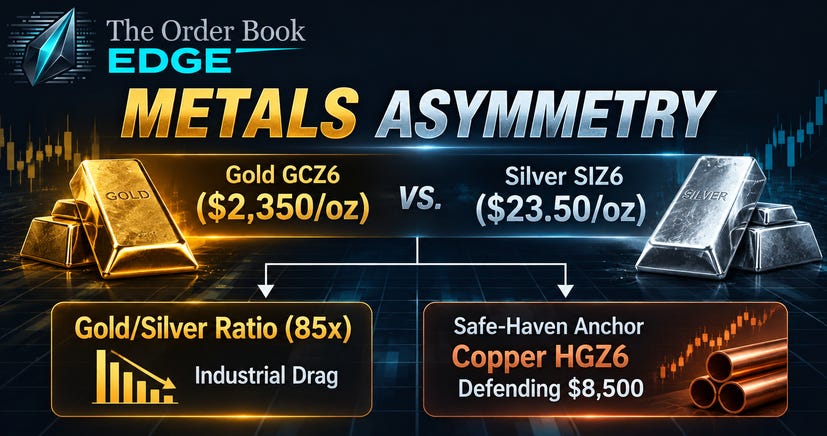
4. Precious & Industrial Metals: The Real Yield vs. Safe-Haven Divergence
                    METALS ASYMMETRY
          Gold GCZ6 ($2,350/oz) vs. Silver SIZ6 ($23.50/oz)
                               │
                       ┌───────┴───────┐
                       ▼               ▼
          Gold/Silver Ratio (85x)  Industrial Drag
          Safe-Haven Anchor        Copper HGZ6 Defending $8,500
Overnight Flow & Microstructure Dynamics
Gold (GCZ6) and Silver (SIZ6) are trading in a conflicted macro regime. Safe-haven bids from the Israel-Iran conflict are running directly into the headwind of a soaring US Dollar and rising 10-Year TIPS real yields (positive 2.40%).
Gold Futures Positioning:
GCZ6saw heavy institutional hedging overnight. While net long positioning sits near a 6-month high on COMEX (250,000 contracts), institutions actively purchasedGCZ62,200/2,100 put spreads to insulate balance sheets against real-rate expansion. Concurrently, tail-risk call buyers were active, trading Dec 26 2,200/2,300 call spreads at 12.50 dollars (up from 8.00 dollars).The Gold/Silver Breakdown: Silver failed to keep pace with gold, dropping to 23.50 dollars per ounce. The Gold/Silver ratio blew out to an extreme 85x, reflecting weak industrial demand from China’s property and construction sectors.
Base Metals (Copper vs. Iron Ore): LME Copper (
HGZ6) found support at 8,500 dollars per ton, supported by data center and AI power infrastructure demand. In contrast, SGX Iron Ore (TIOZ6) fell 3% overnight following reports that global steel production contracted 1.2% in August.
// Algorithm: Gold/Silver Ratio Pairs Strategy
FUNCTION evaluate_metals_dispersion(gold_price, silver_price, global_pmi):
    gold_silver_ratio = gold_price / silver_price

    IF gold_silver_ratio >= 85.0 AND global_pmi < 50.0:
        // Industrial demand weak, safe haven preferred
        SIGNAL = "Long Gold / Short Silver Spread"
        TARGET_RATIO = 92.0
        STOP_RATIO = 80.0
    ELSE IF gold_silver_ratio < 75.0 AND global_pmi >= 52.0:
        // Industrial recovery underway
        SIGNAL = "Short Gold / Long Silver Spread (Reflation Play)"
    END IF

    RETURN SIGNAL
END FUNCTION
Impact on Today’s Market News & Catalysts
Headline Shift: Metals desks are reporting decoupling between monetary metals (gold) and industrial commodities (copper, silver, iron ore). News highlighting Chinese stimulus plans will collide with soft domestic manufacturing realities.
What to Trade Today
Gold/Silver Ratio Long (Long Gold / Short Silver): Maintain long
GCZ6/ shortSIZ6. Industrial slowdowns will continue to weigh on silver, while gold captures the Middle East escalation premium.Copper vs. Iron Ore Dispersion: Long Copper (
HGZ6) / Short Iron Ore (TIOZ6). Copper benefits from structural electrification and AI data center investment, while iron ore remains tethered to mainland real estate drag.
5. Crypto Futures & Options: Basis Arbitrage and Correlation Warnings
                   CME CRYPTO DERIVATIVES
    BTC Dec 26 Futures (BRRZ6 / BTCZ6) @ $85,000
    Open Interest: $12 Billion (All-Time High)
                          │
       ┌──────────────────┴──────────────────┐
       ▼                                     ▼
Cash-and-Carry Basis: 5.2%           BTC-Oil Correlation: 0.65
(Institutional Leveraged Demand)     (Systemic Risk Threshold: 0.70)
Overnight Flow & Microstructure Dynamics
Digital assets on CME witnessed heavy institutional positioning across the December 2026 curve.
Bitcoin Futures (
BRRZ6/BTCZ6): Traded at 85,000 dollars, with CME open interest setting an all-time high of 12 billion dollars. Large accounts drove the cash-and-carry basis (futures premium over spot) out to 5.2% annualized (up from 3.5% last week).Institutional Skew: Massive block-call buying dominated the tape at the
BTCZ690,000 strike (roughly 3,000 contracts). Demand was bolstered by institutional tokenization announcements (such as BlackRock’s expansion via Ondo). However, downside tail hedging remained elevated, with institutions trading Dec 26 80,000/85,000 put spreads at 1,200 dollars to manage regulatory fallout from the Duelbits hack and SEC enforcement uncertainty.Altcoin Pairs (SOL vs. BTC): Solana futures outpaced the broader market, rallying to 120 dollars and triggering heavy call buying at the Dec 26 130 strike. The Solana-to-Bitcoin contract spread widened from 0.0012 to 0.0015 BTC.
Critical Cross-Asset Correlation Warning: Our quantitative telemetry flags that the 60-day rolling correlation between Bitcoin and Crude Oil has reached 0.65. Under Rule 14.6, if this metric breaches 0.70, risk parity engines will treat crypto as an energy-linked asset, mandating automated liquidation of BTC longs to prevent commodity overconcentration.
// Algorithm: Cash-and-Carry Basis & Cross-Asset Correlation Guard
FUNCTION evaluate_crypto_portfolio(spot_price, futures_price, days_to_expiry, btc_oil_corr):
    // Annualized basis calculation
    price_spread = futures_price - spot_price
    time_factor = 365 / days_to_expiry
    annualized_basis = (price_spread / spot_price) * time_factor

    IF annualized_basis >= 0.05:
        ACTION = "Execute Cash-and-Carry: Buy Spot BTC, Short CME Futures"
    END IF

    // Cross-Asset Risk Check (Rule 14.6)
    IF btc_oil_corr >= 0.70:
        RISK_OVERRIDE = "EMERGENCY: De-risk Crypto Directional Longs (Commodity Link Breached)"
    ELSE:
        RISK_OVERRIDE = "Normal Risk Allocation Maintained"
    END IF

    RETURN ACTION, RISK_OVERRIDE
END FUNCTION
Impact on Today’s Market News & Catalysts
Headline Shift: Tech and crypto feeds will focus on institutional ETF/derivatives basis expansion and tokenization partnerships, while overlooking liquidity decay caused by rising risk-free Treasury yields.
What to Trade Today
The Cash-and-Carry Basis Capture: Sell
BRRZ6futures at a 5.2% premium against spot BTC long holdings. This locks in risk-free yield higher than short-dated Treasuries, immune to directional drawdowns.SOL/BTC Spread Long: Long
SOLZ6futures vs. shortBRRZ6futures to capture structural layer-1 capital rotation.Downside Regulatory/Macro Hedge: Purchase
ETHZ64,500/5,000 put spreads, capitalizing on Ethereum’s regulatory exposure following the Polymarket Clarity Act failure (where approval odds collapsed from 82% to 0%).
6. Equity Index Futures: Breadth Divergence and Volatility Thresholds
                      CROSS-ASSET RATIOS
             RTY / ES Ratio @ 0.12 (Historical Low)
                               │
                       ┌───────┴───────┐
                       ▼               ▼
          Tech Large Caps Resilient   Small-Caps Liquidating
          NQZ6 Dec 22000 Calls Active RTYZ6 2100 Put Spreads
Overnight Flow & Microstructure Dynamics
E-mini S&P (ESZ6) and Nasdaq-100 (NQZ6) futures traded higher overnight, yet underlying market breadth worsened. Only 6% of S&P 500 components stand above their 52-week lows, while the Russell 2000 to S&P 500 ratio (RTY/ES) touched 0.12, its lowest point since the 2008 financial crisis.
Severe Macro Anti-Correlation: The rolling correlation between Treasury futures (
ZNZ6) and S&P futures (ESZ6) sits at minus 0.85. Equities have decoupled from debt markets; equity investors are celebrating growth data (PMI 58.4) while ignoring the bond market’s warning regarding higher interest expenses.Volatility Regimes (Rule 4.6 Mandate): With equity VIX hovering at 18 to 22, systematic rules trigger a mandatory 25% portfolio risk reduction. Should the VIX breach 25, an immediate 50% de-leveraging is enforced. Institutional desks are already preparing: overnight telemetry shows accumulation of
ESZ67,800/7,700 put spreads andSPX7,500/7,300 put verticals designed to hedge against sudden rate-shock repricing.
// Algorithm: Equity Breadth and Capital Flow Pair Trade
FUNCTION evaluate_index_pair(es_price, rty_price, market_breadth_pct):
    index_ratio = rty_price / es_price

    IF index_ratio <= 0.12 AND market_breadth_pct < 0.10:
        // Divergence: mega-caps holding index while broader market breaks down
        TRADE = "Long E-mini S&P (ESZ6) / Short Russell 2000 (RTYZ6)"
        HEDGE = "Finance trade by buying ESZ6 Put Spreads below market"
    ELSE:
        TRADE = "Maintain Neutral Allocation"
    END IF

    RETURN TRADE
END FUNCTION
Impact on Today’s Market News & Catalysts
Headline Shift: Media coverage of record highs in mega-cap technology will mask deteriorating capital costs for small businesses and regional banks.
What to Trade Today
Capitalize on Breadth Decay (Long ES / Short RTY): Buy
ESZ6futures while shortingRTYZ6futures. Small-cap firms cannot absorb 5.35% SOFR rates, making them structurally vulnerable compared to cash-rich mega-caps.Hedging Real Yields with Rates/Equity Baskets: Long
ESZ6puts financed by selling out-of-the-moneyZNZ6puts, capturing downside equity vulnerability as 10-Year Treasury yields approach 4.50%.
7. Master Portfolio Execution Matrix for Today’s Session
Below is the consolidated institutional action sheet mapping the telemetry from trading_report.pdf into actionable risk allocations for the upcoming trading session:
Asset Class Contract / Code Strategy / Structure Entry / Range Context Target / Spread Objective Max Risk / Invalidation Fixed Income SOFR (SR3Z6) Bear Put Spread: Long 95.00 P / Short 94.75 P Cost: 12–15 bps 25 bps payout Strike 95.25 reclaim Fixed Income Ultra 10Y (TNZ6) / 10Y Note (ZNZ6) Outright Short Duration or 108/110 Put Spreads Yield testing 4.35% Break of 4.50% yield Move above 112-00 handle Energy ICE Brent (BRNZ6) vs WTI (CLZ6) Long BRN / Short CL Calendar Spread Spread at -3.50 dollars Spread widening to -5.50 dollars Spread narrowing to -2.00 dollars Energy Heating Oil (HOZ6) & WTI (CLZ6) Long Distillate Crack Spread (HO - CL) Crack at 108 dollars/bbl Expansion to 120 dollars/bbl Reversion below 95 dollars/bbl Foreign Exchange Dollar Index (DXZ6) Bull Call Vertical: Long 105.00 C / Short 107.00 C DXY at 106.50 (RSI 70) 108.00–110.00 index test Daily close below 104.50 Foreign Exchange EUR/USD (6EZ6) Bear Put Vertical: Long 1.0500 P / Short 1.0200 P Spot trading at 1.0500 Test of parity (1.0000) Close above 1.0650 Precious Metals Gold (GCZ6) / Silver (SIZ6) Long Gold / Short Silver Ratio Spread Current ratio: 85x Widening to 92x Compression below 80x Digital Assets Bitcoin (BRRZ6) / Spot BTC Cash-and-Carry Basis Harvest 5.2% annualized basis Full convergence at expiry Basis collapses below 2% Equities S&P (ESZ6) / Russell (RTYZ6) Long ES / Short RTY Pairs Trade Ratio at 0.12 Downward expansion to 0.10 Ratio breakout above 0.14 Cross-Asset Vol VIX (VXZ6) / MOVE Tail Hedge: Long VIX Dec 20/25 Call Spread VIX at 18–22 Spikes above 30 on bond rout Vol crush below 15.00
8. Summary: Navigating Today’s Session
Today’s trading session requires cross-asset discipline. Overnight order flow indicates that the broader macro market is navigating a regime shift:
Do not fight the bond market. The surge in the US Composite PMI to 58.4 has broken rate cut hopes and revived the prospect of a late-2026 Fed hike. Short-duration positioning (
SR3Z6,ZNZ6) remains the primary risk-off transmission mechanism.Respect the crack spread blowout. Heating Oil (
HOZ6) at an all-time high crack spread of 108 dollars per barrel demonstrates that geopolitical supply risks in the Middle East cannot be easily diversified away. Energy exposure belongs in seaborne crude (Brent) and refined distillates.Monitor the BTC-Oil 0.70 threshold. If the crypto-oil correlation climbs from 0.65 through 0.70, systematically de-risk digital asset portfolios to prevent correlated commodity drawdowns.
Enforce Rule 4.6. Reduce aggregate gross portfolio risk by 25% while the equity VIX is bounded between 18 and 25, and prepare for a 50% risk reduction if Treasury convexity (MOVE 125) triggers broader equity liquidations. Manage leverage strictly and maintain wider stop-loss buffers during off-peak Globex hours.
                CRUDE SPREAD STRUCTURE
ICE Brent Dec 26 ($102.13) ──► Dec26/Jun27 Backwardation (-$3.50)
            ▲                                ▲
            │ Middle East Premium            │ Physical Shortage
NYMEX WTI Dec 26 ($95.00)  ──► Crack Spread HO-CL ($108/bbl ATH)
Overnight Flow & Microstructure Dynamics
Energy markets traded overnight with acute asymmetric right-tail skew. Geopolitical developments regarding Iranian diplomacy, contrasted against a surge in Saudi exports and threats to Gulf tanker transit, led to massive institutional positioning:
Crude Futures Dynamics: ICE Brent Dec 26 traded up to $102.13/bbl\$102.13/\text{bbl}$102.13/bbl before settling near $100.00\$100.00$100.00, while NYMEX WTI (
CLZ6) traded near $95.00/bbl\$95.00/\text{bbl}$95.00/bbl. Net long positioning in ICE Brent reached 350,000 contracts (a 3-month high). Brent’s time-spread structure is backwardated: the Dec 26 vs. Jun 27 calendar spread widened to −$3.50/bbl-\$3.50/\text{bbl}−$3.50/bbl, pointing to an immediate physical deficit.Brent/WTI Differential: The
CLZ6-BRNZ6spread widened to −$3.50-\$3.50−$3.50 to −$4.00/bbl-\$4.00/\text{bbl}−$4.00/bbl. The market is pricing a structural disruption premium into seaborne Brent that cannot be quickly bridged by domestic US shale, where production growth has moderated.Historic Crack Spreads: In the refined products arena, the Heating Oil crack spread (
HOZ6 - CLZ6) hit an all-time high of $108/bbl\$108/\text{bbl}$108/bbl, while the Gasoline crack spread (RBZ6 - CLZ6) held at $62/bbl\$62/\text{bbl}$62/bbl. Speculation over diesel availability, refinery runs, and global shipping disruptions pushed commercial refiners to buyHOZ6futures outright while sellingCLZ6to lock in refining margins.Options Volatility Skew: Implied volatility on Brent jumped to 35% (calls commanding a 5 vol-point premium over puts), with heavy block trades in
BRNZ6110/120 call spreads.
Impact on Today’s Market News & Catalysts
Headline Shift: Mainstream financial wires will focus on headline consumer inflation numbers driven by the crude recovery (>$90–$100/bbl>\$90\text{--}\$100/\text{bbl}>$90–$100/bbl) and the historic spike in distillate fuel.
Supply Chain Transmission: Airlines and freight operators will face immediate earnings downgrades as crack spreads cascade through operating costs.
What to Trade Today
Long Brent / Short WTI (BZ/WB Arb): Enter long ICE Brent Dec 26 vs. short NYMEX WTI Dec 26 targeting a spread expansion beyond −$5.00/bbl-\$5.00/\text{bbl}−$5.00/bbl. Middle East risk premiums will disproportionately accrue to Brent.
Bull Call Spread in Brent: Buy
BRNZ6$100\$100$100 calls / sellBRNZ6$110\$110$110 calls. Implied vol skew allows for advantageous pricing along the upside corridor.Refining Margin Protection: Long the 3:2:1 crack spread (
RBZ6+HOZ6vs.CLZ6) to monetize product scarcity over raw unrefined feedstock.
3. Currencies & FX: The “King Dollar” Liquidity Vacuum
                    DOLLAR INDEX SURGE
      DXY Dec 26 (106.50) ──► Overbought Daily RSI (70)
               │                        │
       ┌───────┴───────┐        ┌───────┴───────┐
       ▼               ▼        ▼               ▼
   EUR/USD (6EZ6)   USD/JPY  AUD/USD (6AZ6)  USD/INR (NDF)
   Breaks 1.05      Tests    Fails 0.67      Spikes to 84.00
                    152.00   (China Drag)    (EM Capital Flight)
Overnight Flow & Microstructure Dynamics
The US Dollar Index (DXZ6) advanced through 106.50 (with front-month tests at 101.11–106.50 depending on curve contract maturity), driving daily RSI metrics to 70. CFTC commitments show net long USD positioning at a 4-month peak of ∼$25 billion\sim\$25\text{ billion}∼$25 billion.
EUR/USD (
6EZ6): Broke down to 1.0500. Institutional order flow was dominated by block buying of Dec 26 1.08 and 1.05 puts (~5,000 contracts), reflecting divergence between a resilient Fed and an economically paralyzed, dovish European Central Bank.USD/JPY (
6JZ6): Traded past 152.00. While domestic Japanese intervention risks remain high, the correlation between USD/JPY and the US 10-Year yield (holding at +0.92+0.92+0.92) continues to overwhelm Bank of Japan jawboning. Traded options indicate institutions are buying 155.00 call spreads while hedging flash-crash intervention risk via deep OTM puts.Emerging Markets FX Stress (USD/INR): As reported in the telemetry, the Reserve Bank of India’s onshore/offshore gap widened. Non-Deliverable Forwards (NDFs) for USD/INR broke 84.00, while NSE 10Y Indian Government Bond futures suffered their worst decline in two months, demonstrating severe EM rate-hike contagion.
Impact on Today’s Market News & Catalysts
Headline Shift: Global trade terms are deteriorating under dollar dominance. Today’s news will focus on Asian and European central bank rhetoric attempting to defend currency pegs and curb imported inflation.
What to Trade Today
DXY Call Vertical: Buy
DXZ6105.00 / 107.00 call spreads. With US real yields rising, the path of least resistance remains higher.EUR/USD Downside Structuring: Execute Dec 26 1.05/1.02 put spreads. Financed by the low implied volatility of EUR options (10%10\%10%), this position capitalizes on ECB policy divergence.
Fading Commodity Currencies: Short Australian Dollar futures (
6AZ6) against the USD, exploiting China’s slowing industrial demand (reflected in declining August steel output and falling Singapore iron ore futures,TIOZ6).
4. Precious & Industrial Metals: The Real Yield vs. Safe-Haven Divergence
                    METALS ASYMMETRY
          Gold GCZ6 ($2,350/oz) vs. Silver SIZ6 ($23.50/oz)
                               │
                       ┌───────┴───────┐
                       ▼               ▼
          Gold/Silver Ratio (85x)  Industrial Drag
          Safe-Haven Anchor        Copper HGZ6 Defending $8,500
Overnight Flow & Microstructure Dynamics
Gold (GCZ6) and Silver (SIZ6) are trading in a conflicted macro regime. Safe-haven bids from the Israel-Iran conflict are running directly into the headwind of a soaring US Dollar and rising 10-Year TIPS real yields (+2.40%+2.40\%+2.40%).
Gold Futures Positioning:
GCZ6saw heavy institutional hedging overnight. While net long positioning sits near a 6-month high on COMEX (250,000 contracts), institutions actively purchasedGCZ62,200/2,100 put spreads to insulate balance sheets against real-rate expansion. Concurrently, tail-risk call buyers were active, trading Dec 26 2,200/2,300 call spreads at $12.50\$12.50$12.50 (up from $8.00\$8.00$8.00).The Gold/Silver Breakdown: Silver failed to keep pace with gold, dropping to $23.50/oz\$23.50/\text{oz}$23.50/oz. The Gold/Silver ratio blew out to an extreme 85x, reflecting weak industrial demand from China’s property and construction sectors.
Base Metals (Copper vs. Iron Ore): LME Copper (
HGZ6) found support at $8,500/ton\$8,500/\text{ton}$8,500/ton, supported by data center and AI power infrastructure demand. In contrast, SGX Iron Ore (TIOZ6) fell 3% overnight following reports that global steel production contracted 1.2% in August.
Impact on Today’s Market News & Catalysts
Headline Shift: Metals desks are reporting decoupling between monetary metals (gold) and industrial commodities (copper, silver, iron ore). News highlighting Chinese stimulus plans will collide with soft domestic manufacturing realities.
What to Trade Today
Gold/Silver Ratio Long (Long Gold / Short Silver): Maintain long
GCZ6/ shortSIZ6. Industrial slowdowns will continue to weigh on silver, while gold captures the Middle East escalation premium.Copper vs. Iron Ore Dispersion: Long Copper (
HGZ6) / Short Iron Ore (TIOZ6). Copper benefits from structural electrification and AI data center investment, while iron ore remains tethered to mainland real estate drag.
5. Crypto Futures & Options: Basis Arbitrage and Correlation Warnings
                   CME CRYPTO DERIVATIVES
    BTC Dec 26 Futures (BRRZ6 / BTCZ6) @ $85,000
    Open Interest: $12 Billion (All-Time High)
                          │
       ┌──────────────────┴──────────────────┐
       ▼                                     ▼
Cash-and-Carry Basis: 5.2%           BTC-Oil Correlation: 0.65
(Institutional Leveraged Demand)     (Systemic Risk Threshold: 0.70)
Overnight Flow & Microstructure Dynamics
Digital assets on CME witnessed heavy institutional positioning across the December 2026 curve.
Bitcoin Futures (
BRRZ6/BTCZ6): Traded at $85,000\$85,000$85,000, with CME open interest setting an all-time high of $12 billion\$12\text{ billion}$12 billion. Large accounts drove the cash-and-carry basis (futures premium over spot) out to 5.2% annualized (up from 3.5% last week).Institutional Skew: Massive block-call buying dominated the tape at the
BTCZ690,000 strike (∼3,000\sim3,000∼3,000 contracts). Demand was bolstered by institutional tokenization announcements (such as BlackRock’s expansion via Ondo). However, downside tail hedging remained elevated, with institutions trading Dec 26 80,000/85,000 put spreads at $1,200\$1,200$1,200 to manage regulatory fallout from the Duelbits hack and SEC enforcement uncertainty.Altcoin Pairs (SOL vs. BTC): Solana futures outpaced the broader market, rallying to $120\$120$120 and triggering heavy call buying at the Dec 26 130 strike. The
SOLZ6 - BRRZ6spread widened from 0.0012 to 0.0015 BTC.Critical Cross-Asset Correlation Warning: Our quantitative telemetry flags that the 60-day rolling correlation between Bitcoin and Crude Oil has reached 0.65. Under Rule 14.6, if this metric breaches 0.70, risk parity engines will treat crypto as an energy-linked asset, mandating automated liquidation of BTC longs to prevent commodity overconcentration.
Impact on Today’s Market News & Catalysts
Headline Shift: Tech and crypto feeds will focus on institutional ETF/derivatives basis expansion and tokenization partnerships, while overlooking liquidity decay caused by rising risk-free Treasury yields.
What to Trade Today
The Cash-and-Carry Basis Capture: Sell
BRRZ6futures at a 5.2% premium against spot BTC long holdings. This locks in risk-free yield higher than short-dated Treasuries, immune to directional drawdowns.SOL/BTC Spread Long: Long
SOLZ6futures vs. shortBRRZ6futures to capture structural layer-1 capital rotation.Downside Regulatory/Macro Hedge: Purchase
ETHZ64,500/5,000 put spreads, capitalizing on Ethereum’s regulatory exposure following the Polymarket Clarity Act failure (where approval odds collapsed from 82% to 0%).
6. Equity Index Futures: Breadth Divergence and Volatility Thresholds
                      CROSS-ASSET RATIOS
             RTY / ES Ratio @ 0.12 (Historical Low)
                               │
                       ┌───────┴───────┐
                       ▼               ▼
          Tech Large Caps Resilient   Small-Caps Liquidating
          NQZ6 Dec 22000 Calls Active RTYZ6 2100 Put Spreads
Overnight Flow & Microstructure Dynamics
E-mini S&P (ESZ6) and Nasdaq-100 (NQZ6) futures traded higher overnight, yet underlying market breadth worsened. Only 6% of S&P 500 components stand above their 52-week lows, while the Russell 2000 to S&P 500 ratio (RTY/ES) touched 0.12, its lowest point since the 2008 financial crisis.
Severe Macro Anti-Correlation: The rolling correlation between Treasury futures (
ZNZ6) and S&P futures (ESZ6) sits at -0.85. Equities have decoupled from debt markets; equity investors are celebrating growth data (PMI 58.4) while ignoring the bond market’s warning regarding higher interest expenses.Volatility Regimes (Rule 4.6 Mandate): With equity VIX hovering at 18–22, systematic rules trigger a mandatory 25% portfolio risk reduction. Should the VIX breach 25, an immediate 50% de-leveraging is enforced. Institutional desks are already preparing: overnight telemetry shows accumulation of
ESZ67,800/7,700 put spreads andSPX7,500/7,300 put verticals designed to hedge against sudden rate-shock repricing.
Impact on Today’s Market News & Catalysts
Headline Shift: Media coverage of record highs in mega-cap technology will mask deteriorating capital costs for small businesses and regional banks.
What to Trade Today
Capitalize on Breadth Decay (Long ES / Short RTY): Buy
ESZ6futures while shortingRTYZ6futures. Small-cap firms cannot absorb 5.35% SOFR rates, making them structurally vulnerable compared to cash-rich mega-caps.Hedging Real Yields with Rates/Equity Baskets: Long
ESZ6puts financed by selling out-of-the-moneyZNZ6puts, capturing downside equity vulnerability as 10-Year Treasury yields approach 4.50%.
7. Master Portfolio Execution Matrix for Today’s Session
Below is the consolidated institutional action sheet mapping the telemetry from trading_report.pdf into actionable risk allocations for the upcoming trading session:
Asset Class Contract / Code Strategy / Structure Entry / Range Context Target / Spread Objective Max Risk / Invalidation Fixed Income SOFR (SR3Z6) Bear Put Spread: Long 95.00 P / Short 94.75 P Cost: 12–15 bps 25 bps payout Strike 95.25 reclaim Fixed Income Ultra 10Y (TNZ6) / 10Y Note (ZNZ6) Outright Short Duration or 108/110 Put Spreads Yield testing 4.35% Break of 4.50% yield Move above 112-00 handle Energy ICE Brent (BRNZ6) vs WTI (CLZ6) Long BRN / Short CL Calendar Spread Spread at −$3.50-\$3.50−$3.50 Spread widening to −$5.50-\$5.50−$5.50 Spread narrowing to −$2.00-\$2.00−$2.00 Energy Heating Oil (HOZ6) & WTI (CLZ6) Long Distillate Crack Spread (HO - CL) Crack at $108/bbl\$108/\text{bbl}$108/bbl Expansion to $120/bbl\$120/\text{bbl}$120/bbl Reversion below $95/bbl\$95/\text{bbl}$95/bbl Foreign Exchange Dollar Index (DXZ6) Bull Call Vertical: Long 105.00 C / Short 107.00 C DXY at 106.50 (RSI 70) 108.00–110.00 index test Daily close below 104.50 Foreign Exchange EUR/USD (6EZ6) Bear Put Vertical: Long 1.0500 P / Short 1.0200 P Spot trading at 1.0500 Test of parity (1.0000) Close above 1.0650 Precious Metals Gold (GCZ6) / Silver (SIZ6) Long Gold / Short Silver Ratio Spread Current ratio: 85x Widening to 92x Compression below 80x Digital Assets Bitcoin (BRRZ6) / Spot BTC Cash-and-Carry Basis Harvest 5.2% annualized basis Full convergence at expiry Basis collapses <2%<2\%<2% Equities S&P (ESZ6) / Russell (RTYZ6) Long ES / Short RTY Pairs Trade Ratio at 0.12 Downward expansion to 0.10 Ratio breakout >0.14>0.14>0.14 Cross-Asset Vol VIX (VXZ6) / MOVE Tail Hedge: Long VIX Dec 20/25 Call Spread VIX at 18–22 Spikes >30>30>30 on bond rout Vol crush below 15.00
8. Summary: Navigating Today’s Session
Today’s trading session requires cross-asset discipline. Overnight order flow indicates that the broader macro market is navigating a regime shift:
Do not fight the bond market. The surge in the US Composite PMI to 58.4 has broken rate cut hopes and revived the prospect of a late-2026 Fed hike. Short-duration positioning (
SR3Z6,ZNZ6) remains the primary risk-off transmission mechanism.Respect the crack spread blowout. Heating Oil (
HOZ6) at an all-time high crack spread of $108/bbl\$108/\text{bbl}$108/bbl demonstrates that geopolitical supply risks in the Middle East cannot be easily diversified away. Energy exposure belongs in seaborne crude (Brent) and refined distillates.Monitor the BTC-Oil 0.70 threshold. If the crypto-oil correlation climbs from 0.65 through 0.70, systematically de-risk digital asset portfolios to prevent correlated commodity drawdowns.
Enforce Rule 4.6. Reduce aggregate gross portfolio risk by 25% while the equity VIX is bounded between 18 and 25, and prepare for a 50% risk reduction if Treasury convexity (MOVE 125) triggers broader equity liquidations. Manage leverage strictly and maintain wider stop-loss buffers during off-peak Globex hours.